
Equifax Canada’s latest numbers say out loud something dealers already feel. In the second quarter of 2026, the number of new auto loans opened fell 9.2% from a year earlier. Fewer loans. But the average new loan climbed from $34,713 to $36,979 over the same stretch.
So we’re financing fewer people, for bigger amounts. Total auto loan balances still rose, to $179.1 billion, carried by the size of the deals more than the count.
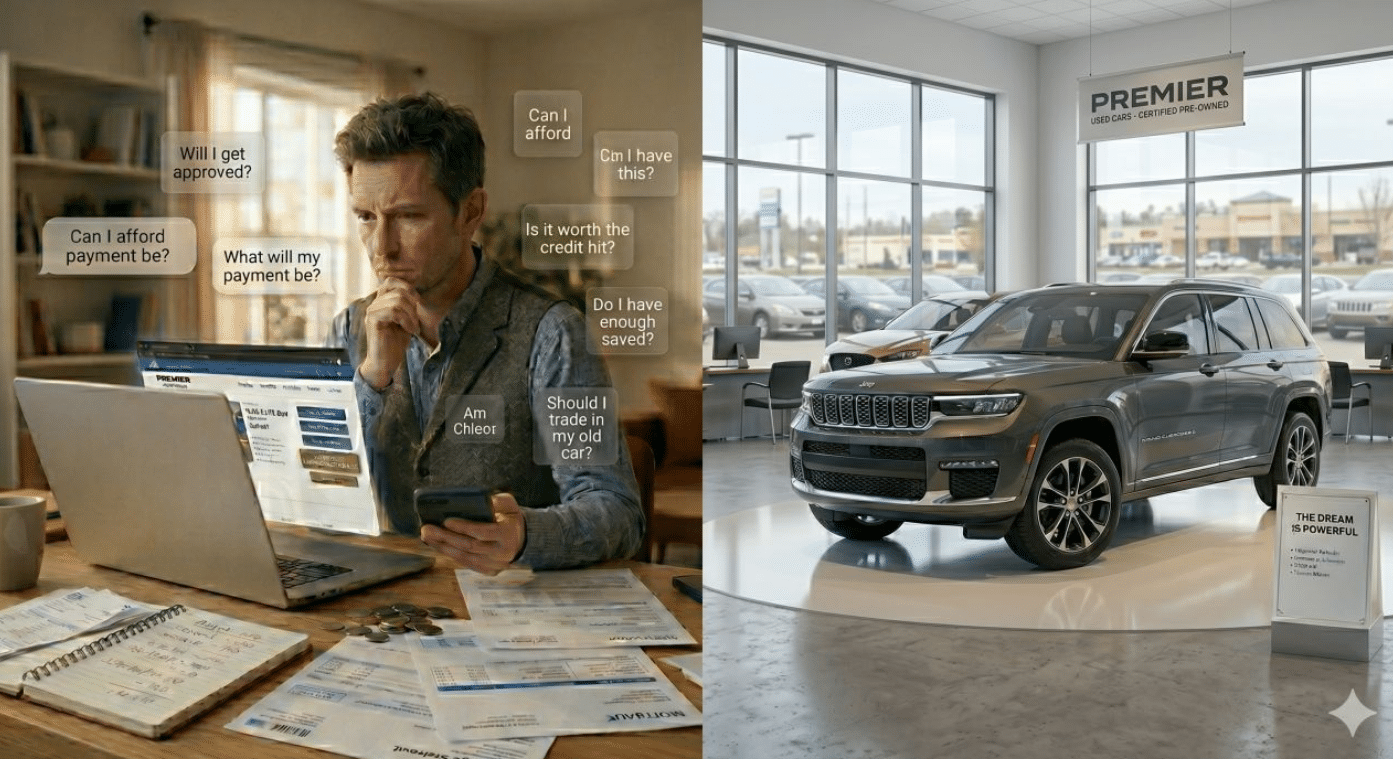
Here’s what that does to a business manager’s day. Back when credit ran wide, a deal pointed at the wrong lender got a second shot, maybe a third, somewhere else. Now that same misread shows up as a decline. And a decline isn’t a lost form. It’s a customer who walks, and usually doesn’t come back.
The portfolio itself is holding, to be fair. Ninety-plus-day auto delinquency actually eased, to 1.10%, mostly on the used side. This isn’t a crash. It’s a tighter room, pickier about how the deal gets built.
Which is where the real work sits, and it sits early. Not at submission. At the moment the credit application comes in. Is the file pointed at the right lenders the first time? Does the structure match what those lenders actually take? Is the first-, second-, or third-chance picture clear before the customer sits down? Get those answers up front and the team spends less time reworking cold files, more time on the ones that can close.
None of this takes the call away from the business manager or the lender. The tool structures. People decide. But in a market that forgives less, a clear financing direction at application time stops being a nice-to-have. It’s the line between a deal you worked and a deal you lost.
That’s the bet a Quebec company like DecisioningIT is making with SAM: give that direction the moment the credit application lands, lined up with how lenders really behave, so every file starts pointed the right way. Profit on a deal follows the discipline of how it’s built. It doesn’t get declared. In a tighter market, that discipline is the whole difference.